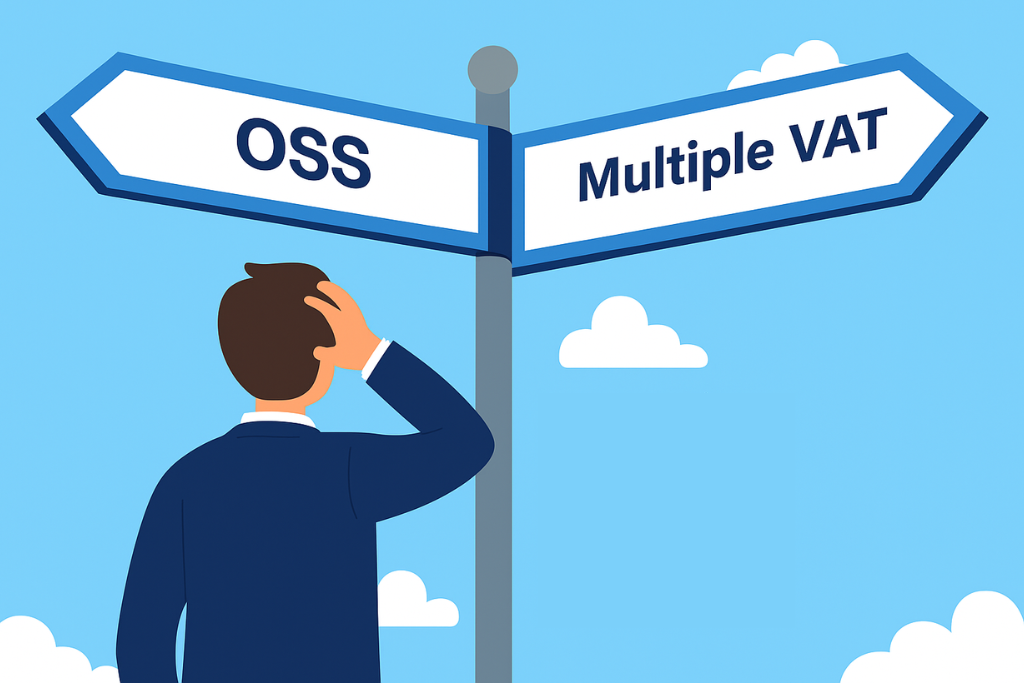
At Cross Border VAT, the most common question we get from EU businesses expanding across member states is: “Should I register for OSS or set up individual VAT registrations in each country?” It’s a fair question, and the answer can literally save you thousands of pounds and countless hours of admin work. Let me break down what we’re seeing in practice and help you make the right choice for your business.
What’s the real difference between OSS and Multiple registrations?
The One-Stop Shop (OSS) system allows you to report and pay VAT for all EU member states through a single portal in your home country. Instead of dealing with 26 different tax authorities, languages, and filing requirements, you handle everything through one interface with quarterly returns.
Multiple VAT registrations mean exactly what it sounds like: separate registrations, separate monthly or quarterly filings, separate payments, and separate correspondence in each country where you sell. We have clients managing up to 15 different VAT registrations, and honestly, it’s a nightmare.
Last month, we helped a software company migrate from multiple registrations to OSS, and the relief was immediate. Instead of juggling 12 different filing deadlines and payment schedules, they now handle everything quarterly through the UK portal.
How much does each option actually cost?
OSS Costs:
- Single registration fee in your home member state.
- One quarterly filing (typically £150-300 per quarter for professional preparation)
- Single payment to your home tax authority.
- Minimal ongoing compliance costs.
Multiple Registration Costs:
- Registration fees in each country (ranging from £50 to £500 per country)
- Monthly or quarterly filings in each jurisdiction (£100 to £250 per filing per country)
- Translation costs for correspondence and documents.
- Currency conversion fees for payments.
- Local representation fees in some countries.
We calculated the annual costs for a client selling to 8 EU countries: OSS came to roughly £1,800 annually for compliance, whilst multiple registrations cost £14,000+ just in filing fees, before accounting for the administrative headaches.
What about administrative burden?
This is where OSS really shines. The European Commission estimates OSS reduces administrative burdens by up to 95% compared to multiple registrations, and our experience confirms this.
OSS Administrative Requirements:
- Quarterly filing in your home language.
- Single portal for all transactions.
- One payment per quarter.
- Correspondence with one tax authority.
Multiple Registrations Administrative Load:
- Monthly/quarterly filings in multiple languages.
- Different VAT return formats for each country.
- Separate payment systems and bank arrangements.
- Managing correspondence from multiple tax authorities.
- Tracking different deadlines and requirements.
We have a fashion client who was spending 2-3 days monthly just managing VAT filings across EU countries. After switching to OSS, their monthly VAT admin dropped to half a day quarterly. That’s roughly 30 hours per year instead of 300+ hours.
When does OSS make sense for your business?
Perfect OSS Candidates:
- EU-established businesses selling B2C across multiple member states.
- Companies selling digital services to European consumers.
- Businesses with consistent cross-border sales patterns.
- Companies want simplified compliance and reporting.
OSS Limitations to Consider:
- Only covers B2C supplies and certain B2B services.
- Can’t be used for goods requiring local VAT registration (like distance selling thresholds)
- Doesn’t cover supplies where VAT is due in the member state of consumption for other reasons.
We had an electronics retailer who thought OSS would solve all their VAT issues, but they were also importing goods that required IOSS registration. OSS handled their EU-to-EU sales perfectly, but they still needed separate compliance for their import operations.
Are there scenarios where multiple registrations make more sense?
Surprisingly, yes. Multiple registrations might be better if:
You Have Significant B2B Sales
If most of your EU sales are B2B, you’ll likely need local registrations anyway for proper invoicing and customer requirements. OSS won’t eliminate the need for local presence in key markets.
You’re Importing Goods Regularly
If you’re storing inventory in multiple EU countries or importing significant volumes, local registrations might be unavoidable regardless of OSS eligibility.
You Want Input VAT Recovery
With multiple registrations, you can potentially recover input VAT in each jurisdiction. OSS doesn’t provide input VAT recovery rights in the same way.
Your Business Model Is Complex
Companies with mixed B2B/B2C sales, physical presence in multiple countries, or complex supply chains often need the flexibility that multiple registrations provide.
What’s the Migration Process Like?
Moving from Multiple Registrations to OSS:
We typically see a 3-6 month transition period. You need to deregister from individual countries (after fulfilling final obligations), register for OSS, and adjust your systems. The process isn’t seamless, but the long-term benefits usually justify the effort.
Starting with OSS from Day One:
Much simpler. Register for OSS before you start selling, set up proper transaction recording, and you’re ready to scale across the EU without additional VAT complexity.
The Hybrid Approach:
Some businesses use OSS for consumer sales and maintain specific registrations for B2B markets or inventory locations. It’s more complex to manage, but it gives maximum flexibility.
How do marketplaces fit into this decision?
If you’re selling on Amazon, eBay, or other marketplaces, OSS becomes even more attractive. Marketplaces handle VAT collection for many transactions, but you still need proper registration for compliance.
OSS allows you to manage marketplace and direct sales through one system, whilst multiple registrations require coordination across platforms and jurisdictions. We have clients using OSS specifically because it simplifies their marketplace compliance across multiple countries.
What’s Coming Next for OSS?
The EU is introducing new SME exemptions that let small firms stay VAT-free up to £85,000-£100,000 EU turnover, but this runs outside OSS. Once you join OSS, you can’t use that exemption.
Starting January 1st, 2025, livestreams, virtual events, and online classes will fall under the same rules as electronically supplied services, expanding OSS coverage for digital service providers.
The trend is clearly toward greater OSS adoption and expanded coverage. The European Commission wants to make cross-border trade as simple as domestic trade, and OSS is its primary tool for achieving that goal.
Making the right choice for your business
In our experience, about 80% of EU businesses selling cross-border benefit significantly from OSS registration. The administrative savings alone justify the switch for most companies, and the cost savings are substantial.
The businesses that struggle with OSS are usually those with complex operational structures or significant B2B requirements. For everyone else, OSS is typically the clear winner.
At Cross Border VAT, we help businesses evaluate their specific situations and make the right choice. We can handle OSS registration and compliance, or if multiple registrations make more sense, we manage those relationships across all relevant jurisdictions.
The key is making an informed decision based on your actual business model, not just assumptions about complexity or cost.
People also ask
Q1. Do I still need local VAT registrations if I use OSS?
A1. Yes, in certain cases. OSS only covers cross-border B2C sales within the EU. If your business stores goods in other EU countries, imports stock, or sells mostly to B2B customers, you still need local VAT registrations alongside OSS. It’s important to assess your sales and supply chain to determine exactly where local registrations remain necessary.
Q2. Can I recover input VAT through OSS or only with local registrations?
A2. OSS does not provide input VAT recovery. If you incur VAT on local purchases or expenses in other EU countries, you must either maintain local VAT registrations in those countries or use the EU VAT refund procedure.
Q3. How long does it take to get set up on OSS?
A3. The registration process is generally straightforward and usually takes a few weeks, depending on your home member state’s tax authority. Once registered, you submit quarterly returns covering all EU cross-border B2C sales through a single portal, reducing administrative workload and the risk of errors.
Q4. What happens if I sell both B2B and B2C in the EU?
A4. You may need a combination of OSS and local VAT registrations. OSS simplifies B2C sales reporting, but B2B transactions often require local VAT compliance to meet invoicing, reporting, and customer requirements. Evaluating your sales mix ensures you choose the most efficient and compliant setup.
Q5. Can I switch from OSS back to multiple registrations if my business model changes?
A5. Yes, but you must deregister from OSS and then apply for local registrations again. Many businesses use a hybrid approach, keeping OSS for B2C sales and local registrations for other needs.
Trying to decide between OSS and multiple EU VAT registrations? We help businesses evaluate their options and implement the most cost-effective compliance strategy.