The European Union is implementing one of the most significant customs policy shifts in decades. From July 2026, the long-standing EUR 150 de minimis threshold will effectively end, replaced by a flat €3 customs duty on low-value imports. This change will fundamentally reshape cross-border e-commerce in the EU and demands immediate attention from international sellers.
What is the EU de minimis threshold?
For over a decade, goods valued below EUR 150 entering the EU have been exempt from customs duties, though VAT has remained payable. This threshold, known as the de minimis exemption, was designed to reduce administrative burdens on customs authorities whilst facilitating small-scale trade.
However, the landscape has changed dramatically. In 2024 alone, approximately 4.6 billion low-value parcels entered the EU, representing roughly 12 million parcels daily. This explosive growth, with over 90% originating from China, has overwhelmed customs systems and created what the European Commission considers an uneven playing field for EU-based retailers.
Why is the EU removing the EUR 150 exemption?
The decision to abolish the de minimis threshold stems from several pressing concerns. EU authorities estimate that up to 65% of small parcels are undervalued to remain below the EUR 150 threshold, facilitating customs fraud and revenue loss. Non-EU sellers have gained a competitive advantage over domestic businesses that must pay full duties on bulk imports.
The global momentum towards tighter customs controls has accelerated this change. Following the United States elimination of its $800 de minimis exemption in August 2025, the EU moved swiftly to prevent diverted e-commerce flows from overwhelming European borders.
The €3 Flat Fee: How will it work?
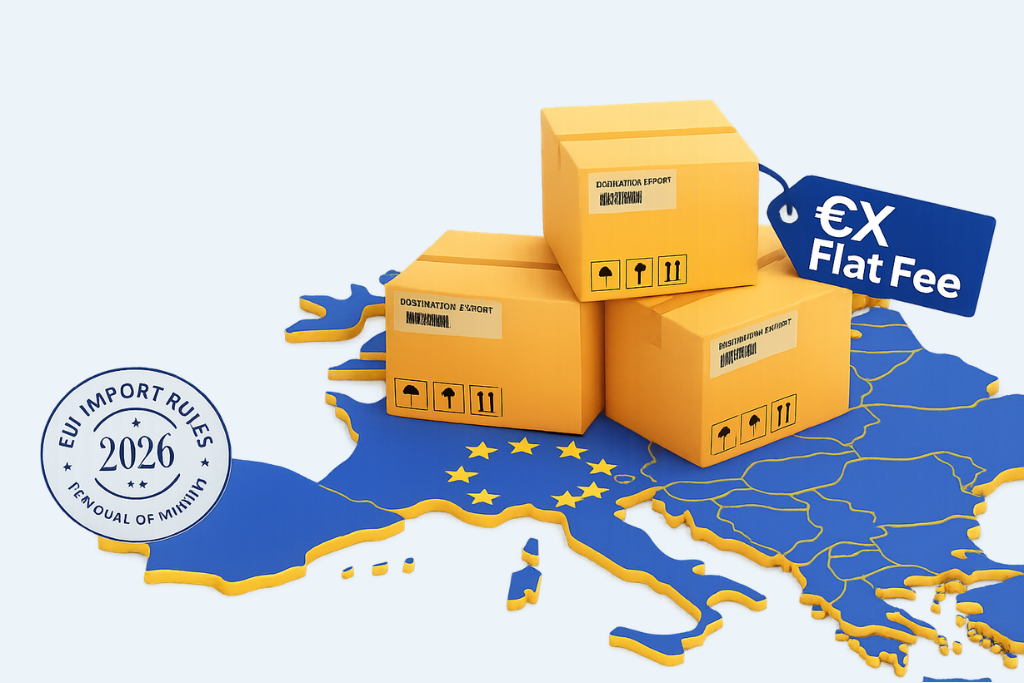
From 1 July 2026, the EU will implement a temporary flat customs duty of €3 per item on goods valued below EUR 150. This interim measure will apply specifically to non-EU sellers registered under the Import One-Stop Shop (IOSS) for VAT purposes, capturing approximately 93% of all cross-border e-commerce imports.
Crucially, the fee applies per item based on tariff classification, not per parcel. If a customer orders three different products shipped together, each item attracts a separate €3 duty. This per-item structure is designed to eliminate the incentive for parcel splitting, a common practice where sellers divide orders into multiple packages to stay below value thresholds.
The flat fee represents a simplified approach whilst the EU develops its permanent solution. By 2028, when the EU Customs Data Hub becomes operational, the system will transition to full tariff-based duty calculations for every import, regardless of value.
What about additional handling fees?
Beyond the €3 customs duty, the European Commission has been discussing a separate EU-wide handling fee of approximately €2 per parcel to offset administrative costs. This fee, still under negotiation, could take effect from November 2026.
However, several Member States have refused to wait. Romania introduced a €5 logistics tax per parcel from January 2026, whilst Belgium, France, and the Netherlands are expected to implement their own handling fees imminently. This patchwork of national measures reflects the urgency with which EU countries are addressing the low-value import challenge.
How will this impact cross-border sellers?
The financial implications are substantial, particularly for businesses built on ultra-low price points. A €10 item will now face a €3 duty (30% increase), plus VAT calculated on the combined value, plus potential handling fees. For sellers of fashion accessories, jewellery, beauty products, and electronics, categories that currently benefit most from duty-free shipping, margins will be squeezed considerably.
Sellers must also navigate increased compliance complexity. Accurate HS code classification becomes critical, as the €3 duty applies per tariff heading. IOSS registration, already essential for VAT compliance, now directly impacts customs treatment. Non-IOSS imports may face even stricter requirements or higher charges once the Commission extends the measure.
What should businesses do now?
Forward-thinking sellers should analyse their EU order data immediately to quantify exposure. How many shipments currently fall below EUR 150? Which product categories will be most affected? What are the specific duty rates for your goods under the new regime?
Pricing strategies require urgent revision. Businesses must decide whether to absorb the additional costs, pass them to customers, or find operational efficiencies to offset the impact. Consider implementing country-specific pricing to reflect varying national handling fees.
Operational models may need fundamental restructuring. Direct fulfilment from outside the EU will become less competitive for many sellers. EU-based warehousing, bulk shipping, and local distribution networks may offer better economics despite upfront costs. Bundling products to increase average order values can help distribute fixed customs costs across more revenue.
Looking ahead: The 2028 permanent solution
The temporary €3 flat fee is merely a stopgap. By March 2028, the EU Customs Data Hub will enable fully automated, item-specific duty calculations based on actual tariff rates. Fashion items might face 12% duties, electronics 0-5%, depending on precise classifications.
This permanent regime will demand even greater precision in product data, real-time customs compliance, and sophisticated integration with EU systems. Sellers who invest now in proper customs infrastructure, accurate classification systems, automated duty calculation, and robust compliance processes will find the 2028 transition far less disruptive.
The elimination of the de minimis threshold represents a fundamental recalibration of cross-border e-commerce. Whilst the changes create challenges, they also offer opportunities for businesses that adapt strategically, invest in EU presence, and build sustainable compliance frameworks.
People also ask
Q1. When exactly does the €3 flat customs duty come into effect?
A1. The €3 flat customs duty on low-value imports takes effect on 1 July 2026. This is a temporary measure that will remain in place until the EU Customs Data Hub launches in 2028, at which point full tariff-based duties will apply to all imports.
Q2. Does the €3 fee replace VAT on imports?
A2. No, the €3 customs duty is in addition to VAT, not a replacement. Import VAT still applies from the first euro under the 2021 e-commerce reforms. Sellers using IOSS collect VAT at checkout, whilst the €3 duty is applied at customs clearance on each item.
Q3. Will the flat fee apply if I ship multiple items in one parcel?
A3. Yes. The €3 duty applies per item based on tariff classification, not per parcel. If you ship three different products together, each attracts a separate €3 charge. This structure specifically targets parcel splitting practices.
Q4. Are EU-based sellers affected by these changes?
A4. EU sellers using the One-Stop Shop (OSS) for intra-EU sales are not directly affected by the €3 duty, which applies specifically to imports from outside the EU. However, EU businesses importing goods from third countries for resale will face these charges, impacting their cost structures.
Q5. How does this compare to the US de minimis removal?
A5. The US eliminated its $800 de minimis threshold in August 2025, imposing duties on all imports immediately. The EU’s approach is more gradual, with a simplified €3 flat fee transitioning to full tariff-based duties by 2028. Both changes reflect the global tightening of customs controls on low-value e-commerce.
Navigate EU customs changes with confidence
The removal of the EU de minimis threshold and introduction of flat fee import duties represent the most significant shift in European cross-border trade in decades. At Cross Border VAT, we specialise in helping international sellers navigate complex VAT and customs compliance across all EU Member States.
Our expert team can help you:
- Analyse your specific exposure to the new customs duties.
- Implement compliant IOSS registration and VAT reporting.
- Restructure your fulfilment model for optimal cost efficiency.
- Prepare for the 2028 transition to full tariff-based duties.
- Navigate country-specific handling fees and requirements.
Don’t let customs compliance challenges derail your EU growth strategy.
Contact Cross Border VAT today for a comprehensive consultation on how these changes affect your business, and how to turn compliance into a competitive advantage.
Get ahead of the July 2026 deadline. Speak to our specialists now.